
金融市场信息可能随时间变化,请以最新公开信息为准。
Analyzing the request reveals the core task: expand the HTML article. The focus will be on the content, particularly the data on Bitcoin’s all-time high pullback depth, translating to Traditional Chinese (Hong Kong) and generating an HTML snippet. This will involve researching historical data and structuring it effectively for an online article.
The initial assessment points to the article’s core topic: analyzing the historical depth of Bitcoin’s pullbacks from all-time highs. The goal is to present this information in a structured, accessible format suitable for an online article in Traditional Chinese (Hong Kong). The provided structure needs expansion, with an emphasis on data-driven insights and technical context.
The expansion requires a clear definition of “pullback depth,” including the metrics and statistical baselines used in its calculation. Investigating different methodologies for defining and quantifying these pullbacks is the next logical step, focusing on practical applicability within the context of the article. This step is crucial for establishing the foundation for accurate analysis.
I need to outline the various major cycles of Bitcoin price movements to understand pullback depth. These cycles need to include the reasons for each specific correction, and the signals that preceded those bottoms. This needs to be done with accuracy and completeness.
Examining historical price charts and relevant market data will be necessary to identify significant all-time highs and their subsequent drawdowns. The next task involves calculating the percentage decline from peak to trough for each identified pullback.
A structured presentation of these findings should consider providing a table or chart summarizing each cycle’s pullback depth, duration, and potential contributing factors. Further research to analyze these cycles is needed, including on-chain metrics, macro-economic conditions, and market sentiment, and how these affected pullback depths.
Diving into on-chain data, I must investigate metrics like transaction volume, active addresses, and mining difficulty, and how these metrics correlated with previous market cycles and pullbacks. Understanding these mechanics might require integrating data from multiple sources.
The impact of macroeconomic factors, like interest rates, inflation, and global economic events, on Bitcoin’s price corrections requires analysis. The analysis needs to include the role of regulatory changes, market sentiment shifts, and external economic shocks.
The emergence of Bitcoin ETFs and their impact on market dynamics will need to be studied. Determining how institutional investments and changes in market structure affect pullback behaviors is critical. This analysis will guide the formation of conclusions about future market cycles.
Comparing and contrasting different market cycles is the next step. Identifying any similarities or differences in pullback characteristics could point towards underlying patterns. Such analysis will aid in evaluating current market conditions and estimating potential future scenarios.
The identification of potential “bottom signals” that indicate the end of a pullback is important. These signals might include technical indicators, on-chain metrics, market sentiment analysis, and external factors. This is a critical factor for risk management.
Risk management strategies should be integrated to address the cyclical nature of Bitcoin. This includes diversification, dollar-cost averaging, and understanding market volatility, considering the historical patterns.
A section should be included on the role of Bitcoin mining cycles and their impact on market corrections. Analysis of the halving events, miner capitulation, and their effects on price will require an in-depth review.
I will delve deeper into the interplay between market sentiment and pullback depth. News events, social media trends, and investor behavior influence the extent of market corrections. This requires a thorough examination of these dynamics.
The article should provide practical guidance on navigating Bitcoin’s volatility. Clear, actionable insights for investors based on historical data analysis are a key deliverable. This includes outlining risk management techniques and long-term investment strategies.
The goal is to provide a comprehensive, data-driven analysis of Bitcoin’s historical pullback depths, offering valuable insights for investors. The article will cover market cycles, technical indicators, on-chain metrics, macroeconomic factors, and risk management. This will require the integration of diverse data.
I’m considering how to best present the data on pullback depth, possibly using a tabular format to facilitate comparisons across different cycles. I will explore various data visualization techniques to enhance clarity and readability.
The content needs to be factually accurate and unbiased. Verifying the information from multiple reputable sources is essential. The focus will be on delivering an objective assessment.
The target audience is individuals interested in Bitcoin investments. The article’s language should be clear and accessible, avoiding excessive jargon. This requires providing context and explanations.
The structure of the article must be logical. I will follow a clear narrative flow that guides readers from an introduction to analysis. The format should be easy to follow.
The introduction needs to establish the importance of understanding Bitcoin’s historical pullback depths for making informed investment decisions. It should highlight the volatile nature of the cryptocurrency market. This will set the stage for the analysis.
The section on “Measurement Criteria and Statistical Baseline” will define the methodology for calculating pullback depth. It will cover the criteria for identifying all-time highs and subsequent troughs. This will clarify the analytical approach.
“Major Cycle Depth Review” will delve into individual market cycles. Each cycle will be analyzed in terms of its all-time high, the subsequent pullback depth, the duration of the downturn, and any significant contributing factors.
The article needs to incorporate recent market events and their impact on Bitcoin’s price
Focusing on structuring the article, I will address the analysis of Bitcoin’s historical drawdowns. The initial plan involves defining and calculating pullback depth using arithmetic and logarithmic scales, considering drawdown duration versus “time underwater,” and distinguishing peak-to-trough dynamics from trough-to-recovery.
The aim is to clarify the fundamental difference between calculating drawdowns from all-time highs and standard deviation volatility. Each macro bear market will require a detailed explanation. This will be integrated into the HTML document using a table and contextual narratives to maintain reader engagement.
Specifically, I need to elaborate on the 2011, 2013-2015, 2017-2018, and 2021-2022 market cycles. The focus will be on the core drivers behind each drawdown. I need to explain the causes for each pullback, and the signals that preceded those bottoms, and integrate that into the HTML snippet.
比特幣的價格軌跡始終伴隨高度劇烈的波動。每當一輪強勁的牛市將價格推向歷史新高(All-Time High, ATH)後,市場往往會進入漫長且具備高度破壞性的深度調整期。客觀評估市場週期與資產風險,必須深入量化比特幣歷史高位回調幅度。回顧比特幣誕生以來的數輪大級別牛熊轉換,從回調幅度、盤整時長、宏觀驅動力以及鏈上底層數據中提煉規律,是構建理性投資框架與風險管理體系的重要基石。
歷次週期的宏觀回撤數據多由行業主流數據終端與鏈上分析機構進行標準化統計。由於早期加密資產交易平台流動性高度碎片化,報價存在顯著滑點與平台溢價,加之統計口徑(如採用日線收盤價或極端插針價格)的差異,不同來源的極端值可能存在細微出入。然而,這些歷史序列數據精確勾勒出了比特幣週期的宏觀波動邊界,為評估資產估值中樞提供了清晰的坐標系。
一、計算基準、統計口徑與分析維度
在量化金融領域,歷史高位回調幅度(Maximum Drawdown from ATH)代表資產自某一週期的峰值價格下跌至宏觀底部最低點的百分比跌幅。其標準計算公式為:
在實際統計與跨週期對比時,需嚴格釐清以下三項統計口徑與維度:
- 收盤價(Close)與日內極值(Wick/Extreme):採用 UTC 零點的日線收盤價計算,能有效過濾短暫的流動性真空插針,平滑異常噪音;若採用日內極低價,所體現的極端拋售幅度通常會擴大 2% 至 5%。
- 週期級別與中段調整界定:宏觀週期回調特指牛市終結後的週期性熊市大底;而牛市中途出現的流動性去槓桿(如 20% 至 40% 的急跌)屬於中繼回調,二者在持續時間與籌碼結構上有本質區別。
- 回撤的三維度評估體系:
- 回撤深度(Depth):價格自峰頂下挫的百分比總量;
- 探底時長(Drawdown Duration):從創下歷史高點到觸及該輪週期最低點所需的月數;
- 水下修復週期(Underwater / Recovery Time):價格自最低點重新攀升並突破前一輪歷史最高價所需的總時間。
二、歷次主要週期深度回調全景拆解
自 2009 年創世區塊誕生以來,比特幣經歷了四次完整的宏觀牛熊轉換。以下整理歷次週期的頂部、底部、回調幅度及時間跨度數據:
| 週期高點 | 高點時間 | 其後低點 | 最大回調幅度 | 高點至低點時長 | 低點重返前高時長 |
|---|---|---|---|---|---|
| 約 32 美元 | 2011年6月 | 約 2.0 美元 | 約 −93.8% | 約 5 個月(160 天) | 約 15 個月(2013年2月修復) |
| 約 1,163 美元 | 2013年11月 | 約 152 美元 | 約 −86.9% | 約 14 個月(410 天) | 約 25 個月(2017年1月修復) |
| 約 19,800 美元 | 2017年12月 | 約 3,120 美元 | 約 −84.2% | 約 12 個月(365 天) | 約 24 個月(2020年12月修復) |
| 約 69,000 美元 | 2021年11月 | 約 15,480 美元 | 約 −77.5% | 約 12 個月(375 天) | 約 15 個月(2024年3月修復) |
從上述統計中可以提煉出數個關鍵規律:
- 深度中樞穩定:歷史上四輪熊市大底的回調幅度中位數落在 −84% 至 −86% 之間。
- 探底時長高度收斂:除 2011 年早期市場流動性極端匱乏導致探底僅耗時 5 個月外,後續三輪成熟週期的尋底過程均精確維持在 12 至 14 個月(約 365–410 天)。
- 收復失地耗時較長:從熊市最低點重新回升至突破前高,通常需要歷經 15 至 25 個月的漫長蓄勢,整個「水下週期」平均長達 3 年左右。
三、歷次深度回調的核心成因與宏觀驅動因子
雖然歷次週期的技術面回撤幅度在百分比上呈現規律性,但背後引爆流動性危機與籌碼踩踏的宏觀環境與微觀結構各有其獨特性:
1. 2011 年:早期基礎設施脆斷與黑天鵝衝擊
2011 年比特幣首次突破 30 美元大關,隨後市場遭遇了早期最大交易平台 Mt. Gox 的安全審計漏洞事件,大量比特幣被拋售至訂單簿。在缺乏做市商機制、深度極為脆弱的早期環境下,極小的賣單即造成流動性斷層,價格在短短數月內暴跌逾 93%。
2. 2013–2015 年:交易所破產與行業信用危機
2013 年底,比特幣因全球媒體關注與早期投機狂熱攀升至 1,160 美元上方。隨後監管政策收緊,特別是 2014 年初承擔全球逾七成交易量的 Mt. Gox 宣布因黑客攻擊丟失 85 萬枚比特幣並申請破產保護。行業最大託管中介的崩塌摧毀了市場信心,引發長達 14 個月的陰跌探底,跌幅達 87%。
3. 2017–2018 年:ICO 泡沫出清與做空機制建立
2017 年的牛市由以太坊智能合約引發的全球 ICO 狂潮推動,比特幣逼近 20,000 美元。泡沫破裂後,項目方為應對營運開支大量拋售儲備資產;與此同時,芝加哥商品交易所(CME)於 2017 年 12 月正式推出比特幣期貨合約,機構投資者首次獲得正規的合規做空工具,推動市場估值回歸理性,最終探底 3,120 美元,回調幅度達 84%。
4. 2021–2022 年:宏觀加息週期、去槓桿與機構連環暴雷
2021 年底比特幣觸及約 69,000 美元峰值,隨後全球主要央行為對抗高通脹開啟了數十年來最激進的加息週期,全球風險資產流動性急劇收縮。在此背景下,加密行業內部積累的高槓桿借貸協議爆發系統性危機:2022 年 5 月 Terra/Luna 算法穩定幣崩盤、三箭資本(3AC)破產、Celsius 及 Voyager 倒閉,最終在 11 月引發全球頂級衍生品交易所 FTX 暴雷清算,將比特幣價格壓制至 15,480 美元,全週期回調約 77.5%。
四、多頭中段回調 vs 宏觀週期見頂:識別矩陣
在強勢多頭行情中,比特幣經常出現大幅度的中途洗盤。如果無法準確識別「多頭中繼調整」與「宏觀熊市啟動」,極易在牛市中段恐慌割肉,或在牛市頂部盲目加倉。兩者的核心維度差異如下:
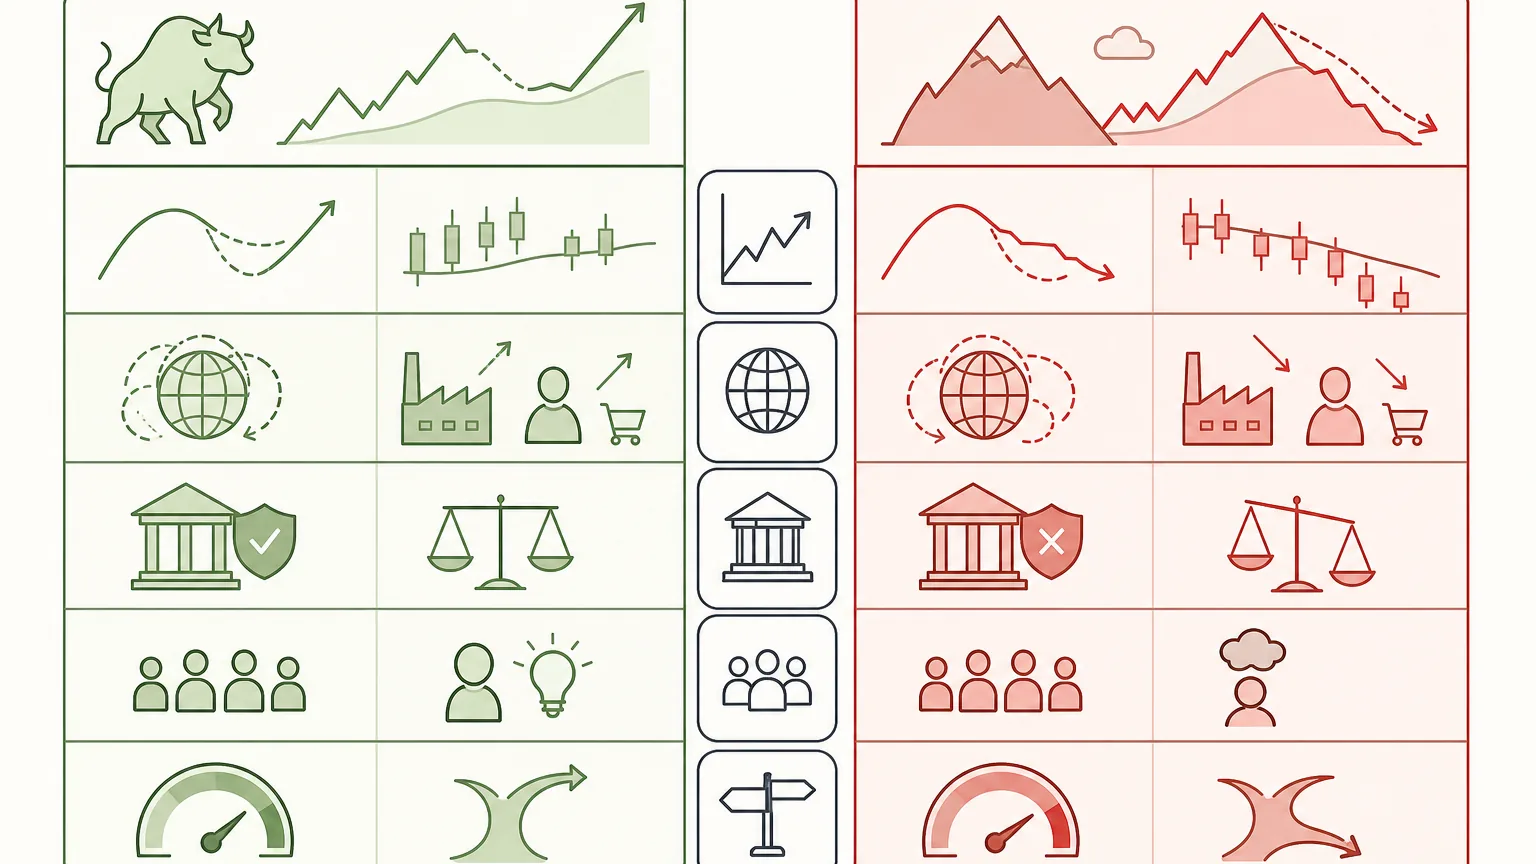
| 比較維度 | 多頭中段回調(Bull Market Correction) | 宏觀週期見頂(Macro Bear Market) |
|---|---|---|
| 典型跌幅空間 | −20% 至 −35%(極端行情可達 −50%) | −75% 至 −85% |
| 調整持續時長 | 2 週至 3 個月內迅速完成去槓桿 | 12 至 14 個月持續陰跌與盤整 |
| 鏈上長期籌碼動向 | 長期持有者(LTH)微量減持或持續增持 | 長期持有者在頂部大量派發(Distribution) |
| 宏觀流動性背景 | 貨幣政策整體寬鬆,短期情緒過熱 | 央行流動性緊縮、實體經濟衰退或信用破裂 |
| 衍生品資金費率 | 快速由正轉負,短線爆倉後迅速回歸中性 | 長期處於低位或負值,未平倉合約持續萎縮 |
歷史典型中段調整案例:
- 2017 年牛市進程中:比特幣在攀升至 20,000 美元的過程中,經歷了多達 5 次幅度在 −30% 至 −40% 的中段回調,每次調整均在數週內收復並再創新高。
- 2021 年 5 月至 7 月:受算力大規模遷徙及衍生品高槓桿清算影響,比特幣自 64,800 美元跌至 29,000 美元,回調幅度達 −54%,盤整約 3 個月後於同年 11 月創下 69,000 美元新高。
- 2024 年 3 月至 8 月:在創下 73,700 美元歷史新高後,受日元套息交易平倉及宏觀不確定性影響,價格最低回撤至約 49,000 美元,回調幅度約 −33%,隨後再度重回上升趨勢。
五、為什麼比特幣的回調幅度呈現逐輪收窄趨勢?
回顧比特幣歷史高位回調幅度序列:−93.8% → −86.9% → −84.2% → −77.5%,其最大回撤深度呈現出清晰的收窄趨勢。這一演進並非偶然,而是由以下深層結構性轉變所決定:
- 市值體量擴大帶來的慣性增強:隨著比特幣總市值突破萬億美元量級,將價格推低相同百分比所需的實質淨流出資金量呈幾何級增長,資產的抗衝擊韌性自然提高。
- 投資者結構由散戶主導轉向機構配置:現貨 ETF(如 BlackRock IBIT、Fidelity FBTC)的推出以及主權基金、退休基金的配置,為比特幣注入了具有長線資產配置視角(Buy-and-Hold)的黏性資本。這類資金具有預先設定的再平衡機制(Rebalancing),在資產下跌時傾向於被動補倉而非恐慌拋售。
- 衍生品流動性深化與對沖機制完備:在 2017 年之前,投資者規避風險的主要手段是將現貨直接拋售換取法幣;現代加密市場具備深度的永續合約、交割合約及期權市場,機構可透過買入保護性認沽期權(Protective Puts)或期現套利(Basis Trade)對沖下行風險,減少了現貨市場的直接拋壓。
六、宏觀觸底訊號的多維交叉驗證體系
精確預測比特幣週期的絕對價格底部極具挑戰,但在鏈上分析(On-Chain Analysis)與量化金融視角下,宏觀底部區域具有高度一致的統計特徵。以下六項核心指標構成了有效的底部識別矩陣:
1. MVRV Z-Score 進入深度低估區間
MVRV Z-Score 衡量比特幣流通市值(Market Value)與已實現市值(Realized Value,即鏈上每枚幣最後一次移動時的成本總和)的標準差偏離程度。在歷史所有大週期熊市底部(2011、2015、2018、2022),MVRV Z-Score 均跌入 0 以下或綠色區間(0.1 以下),表明全網籌碼處於極端帳面浮虧狀態,賣方動能耗盡。
2. 跌破全網已實現價格(Realized Price)
已實現價格代表鏈上所有比特幣的平均取得成本。當現貨市場價格跌破已實現價格時,意味著市場整體處於「水下負收益」階段。歷史數據顯示,現貨價格低於已實現價格的持續時間通常為 2 至 6 個月,是極佳的宏觀定投價值區間。
3. 短期持有者(STH)與長期持有者(LTH)成本倒掛
在週期底部,短期持有者已實現價格(STH Realized Price)往往會跌破長期持有者已實現價格(LTH Realized Price)。這種結構性倒掛反映了最後一批追高入場者完成全面止蝕割肉,籌碼以極低折扣重新集中沉澱至堅定持有者手中。
4. 礦工投降訊號(Hash Ribbons)
當比特幣價格跌破多數礦企的邊際關機成本線時,高成本礦工被迫關機並拋售庫存比特幣支付電費,導致全網算力(Hashrate)出現停滯或負增長。當算力 30 天移動平均線向上穿越 60 天移動平均線時(Hash Ribbons 金叉),往往標誌著礦工投降階段結束,宏觀底部確立。
5. 衍生品資金費率深度轉負與持倉量清算
在熊市末期的極端恐慌中,永續合約資金費率(Funding Rate)會連續數週維持負值,反映散戶與投機者集中進行追空押注;伴隨未平倉合約(Open Interest)的斷崖式下跌,空頭擠壓(Short Squeeze)往往成為啟動新一輪反彈行情的直接技術催化劑。
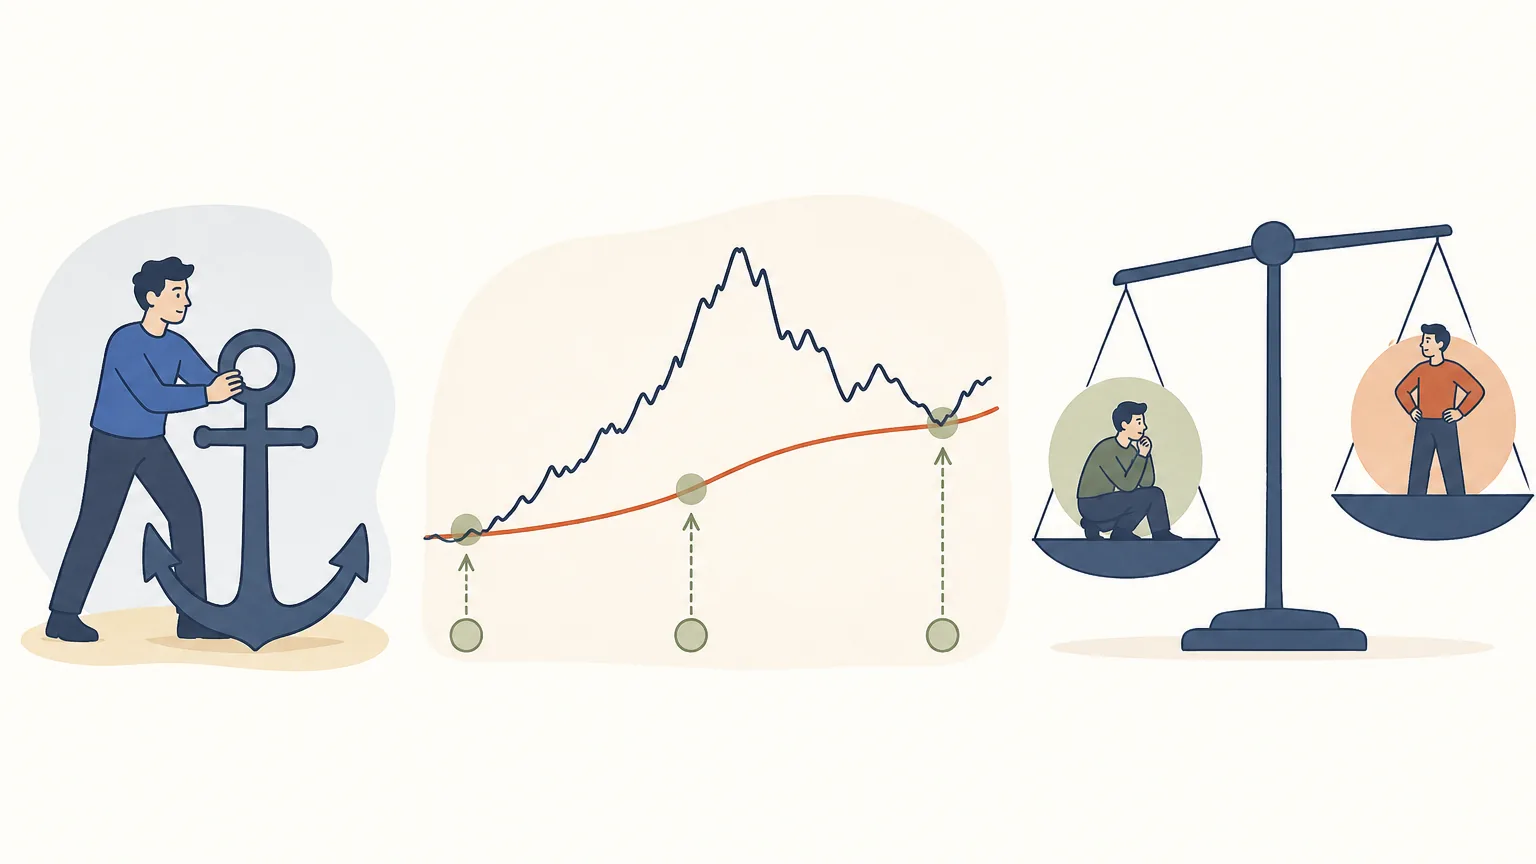
6. 200 週移動平均線(200-Week SMA)估值錨定
在技術圖表上,對數坐標下的 200 週移動平均線長期被視為比特幣的生命線中樞。除 2020 年 3 月流動性危機及 2022 年 FTX 事件期間曾短暫跌破該均線外,歷史上每一次觸及 200 週均線均對應宏觀週期的風險收益比最高點。
七、回撤應對體系與資金管理實務
面對比特幣的高波動與潛在深度回撤,制定具備可執行性的資金管理策略遠比盲目猜測價格頂底更為重要:
1. 階梯式網格定投法(Drawdown-Based DCA)
放棄「單點精確抄底」的思維,轉而將回調幅度作為倉位釋放的觸發條件。例如:當價格自 ATH 回撤達到 −30%、−50%、−65%、−75% 時,按遞增比例(如 10%、20%、30%、40%)分配儲備流動性,有效平攤持倉成本。
2. 現金流儲備與水下心理週期規劃
歷史數據證明,比特幣自深跌修復至前高往往需要長達 2 至 3 年。投資者必須確保配置於虛擬資產的資金在 24 至 36 個月內無被動流動性變現需求,避免在市場最恐慌的估值底部被迫止蝕離場。
3. 嚴格杜絕底部槓桿博弈
在週期底部或探底末期,市場往往會出現多次日內 10% 至 20% 的上下震盪插針行情(洗盤與去槓桿)。在此區間使用槓桿合約極易遭遇雙向爆倉,持有現貨並將資產存入合規冷錢包是穿越週期的最佳實踐。
八、常見問題(FAQ)
Q1:比特幣歷史高位回調幅度一般是多少?
在過往四輪主要的宏觀週期中,比特幣自歷史高點跌至週期底部的最大回調幅度分別約為 −93.8%(2011年)、−86.9%(2013–2015年)、−84.2%(2017–2018年) 及 −77.5%(2021–2022年)。歷史大週期回調幅度的中位數落在 −84% 至 −86% 區間。
Q2:比特幣從高點跌到底部通常需要多長時間?
除 2011 年早期市場歷時約 5 個月外,2013 年、2017 年與 2021 年三輪週期的下行探底階段均維持在 12 至 14 個月(約 365 至 410 天),展現出高度穩定的時間週期對稱性。
Q3:現貨 ETF 獲批後,未來熊市的回調幅度還會達到 80% 嗎?
從歷史趨勢來看,隨著資產體量擴大、機構配置佔比提升以及對沖工具的完善,比特幣的週期回撤幅度呈現遞減趨勢(−93% → −86% → −84% → −77%)。在現貨 ETF 與傳統金融資本常態化配置的背景下,市場流動性深度顯著提升,未來宏觀回調幅度進一步收窄至 −50% 至 −70% 區間的概率正逐步增加,但仍需警惕全球宏觀流動性收緊與系統性黑天鵝風險。
Q4:如何判斷當前回調是牛市回撤還是進入了熊市?
核心區分依據在於跌幅空間、調整時長與鏈上籌碼結構。牛市中繼回調通常在 2 週至 3 個月內完成,跌幅多在 20% 至 35%(極端行情約 50%),長期持有者並未出現大規模派發;而進入宏觀熊市則表現為持續長達約一年的趨勢性下行,跌幅普遍超過 70%,且伴隨鏈上已實現利潤歸零及宏觀流動性全面緊縮。
Q5:什麼是水下修復週期(Underwater Duration)?
水下修復週期指比特幣從跌破前高、經歷熊市探底,再到重新攀升並突破前一輪歷史高價所需的全部時間。歷史上比特幣的水下修復週期平均在 3 年左右(約 36 至 40 個月),要求投資者必須做好長期的資產流動性安排。


